Bank Impact Notes
Interest rates and medical bills both move with the economy. Your HSA sits right where they meet.
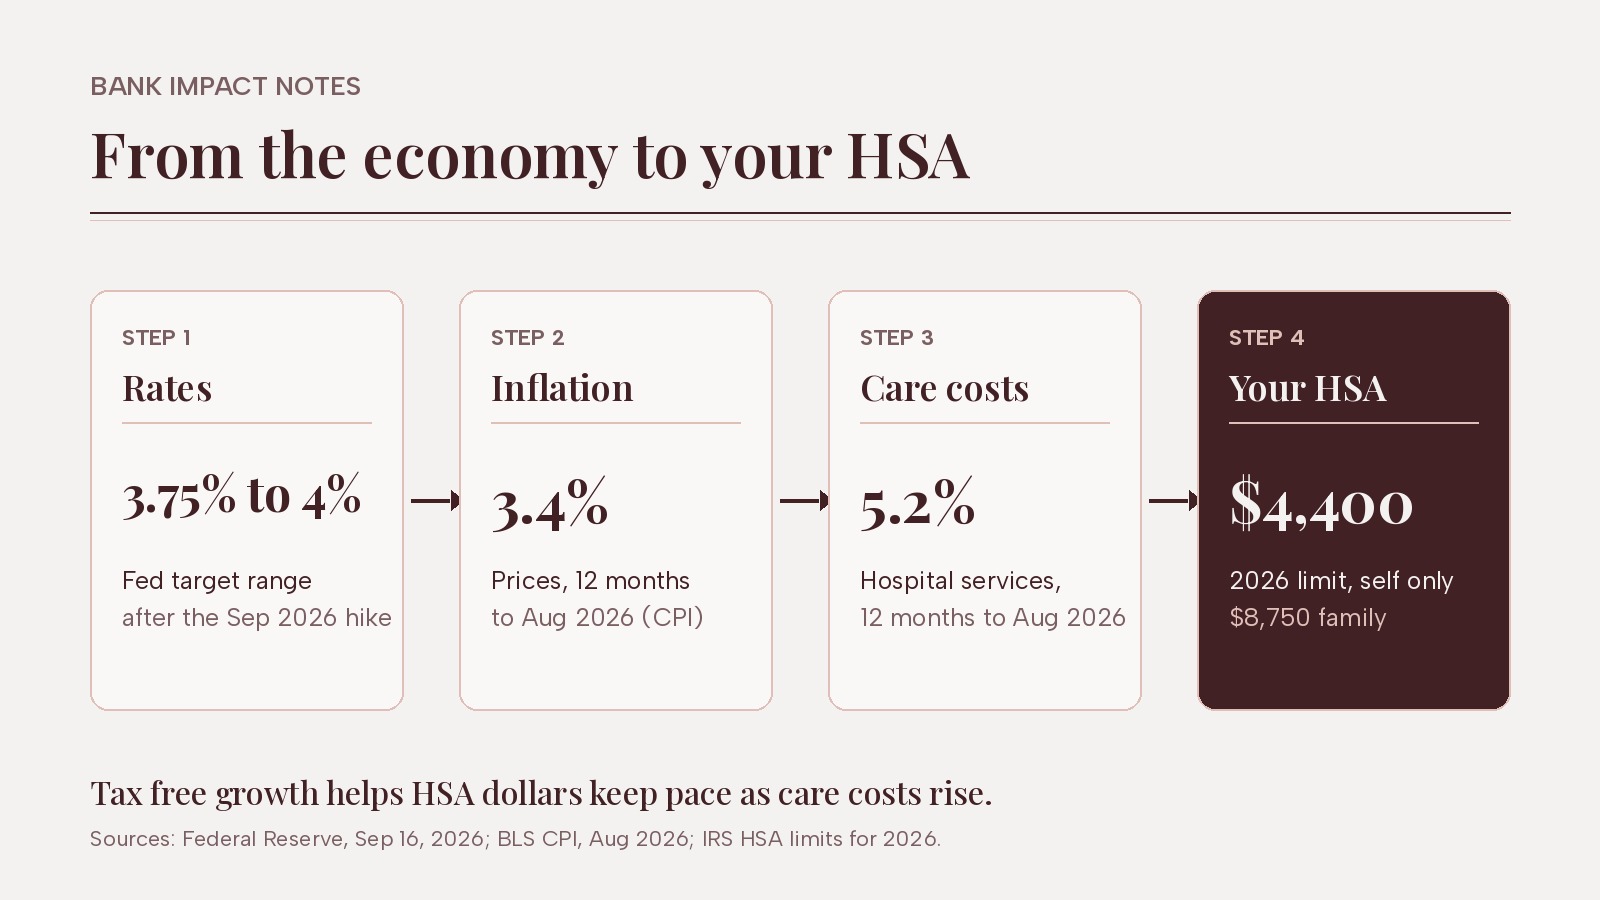
Where the economy meets your HSA
Prices rose 3.4% in the year to August, and hospital services rose 5.2%. To cool inflation, the Fed raised its target range to 3.75% to 4% in September. Higher rates can lift what cash earns, while rising care costs make every saved dollar count. To see how those rates spread, read how interest rates shape liquidity and why AI now costs more to build.
Why the HSA stands out
With an eligible high deductible plan, contributions are tax deductible, growth is tax free, and withdrawals for qualified medical costs are tax free. For 2026 you can save up to $4,400 alone or $8,750 for a family, rising to $4,500 and $9,000 in 2027.
Pay now, grow later
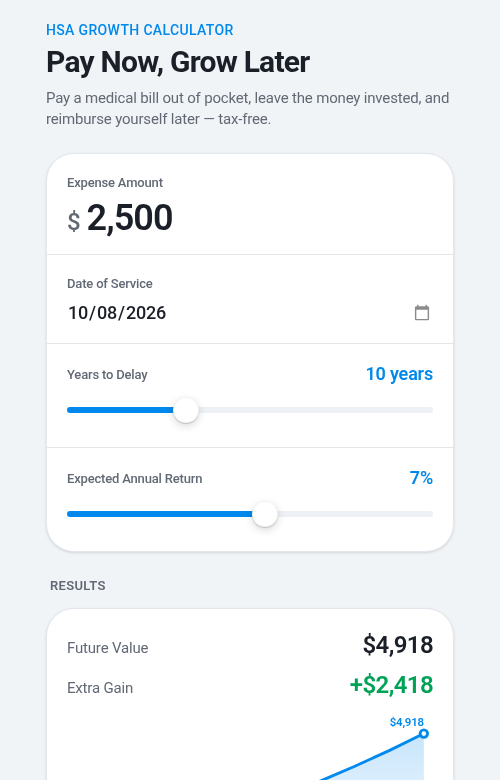
You can also pay a bill out of pocket, leave your HSA invested, and reimburse yourself later for qualified costs incurred after you opened it. My calculator shows the idea: a $2,500 bill left invested for 10 years at an assumed 7% could grow to about $4,918. Returns are never guaranteed.
The takeaway
Care costs rise with the economy. Tax free HSA growth helps you keep pace.
Sources: BLS CPI, Aug 2026 · Fed statement, Sep 2026 · IRS 2026 HSA limits · IRS 2027 HSA limits · IRS Pub 969


Leave a Reply