What Changed for Savers
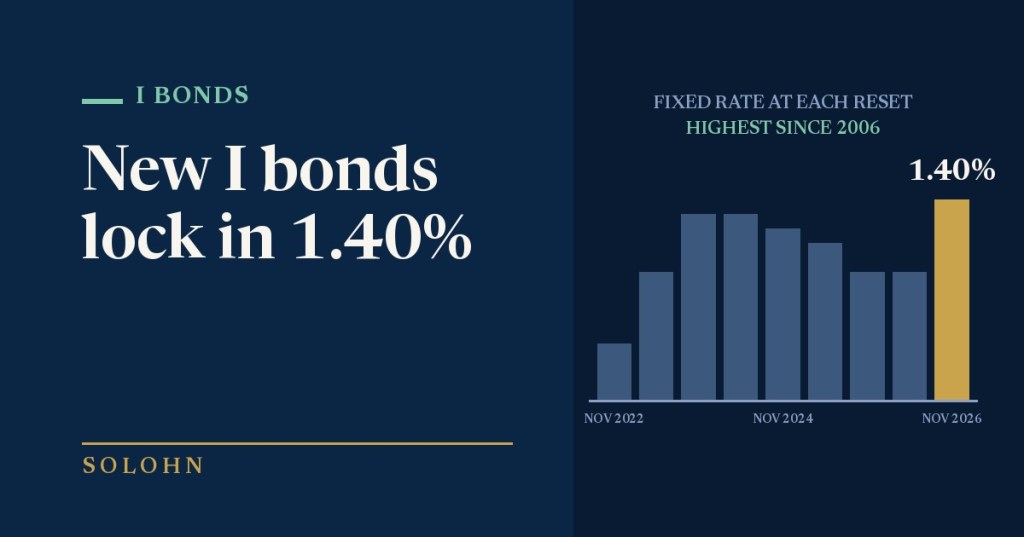
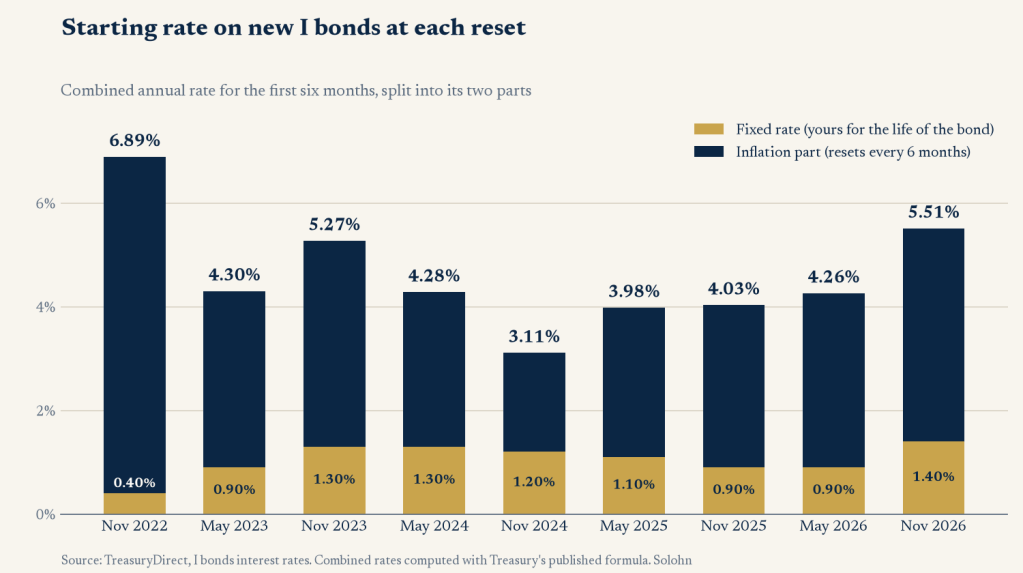
New I bonds pay 5.51% a year for their first six months, the highest starting rate since November 2022. But the number worth your attention is smaller: a 1.40% fixed rate that stays with the bond for up to 30 years.
Treasury reset the rates on Nov. 1. Here is what changed and whether buying before year end makes sense.
Where does 5.51% come from?
Every I bond rate has two parts. The fixed rate is set when you buy and never changes. The inflation rate follows the Consumer Price Index and resets every six months. For bonds bought from Nov. 1, 2026 through April 30, 2027, the fixed rate rose to 1.40% from 0.90%, and the six month inflation rate is 2.04%. Together, that works out to 5.51% a year.
Why is the fixed rate the real news?
The inflation part will move. If prices cool, it falls. The fixed part does not. Treasury has not set a fixed rate this high since November 2006, and as recently as 2022 it was 0%. A bond bought this winter should earn about 1.40% a year above inflation, as measured by CPI, for as long as you hold it.
Put $10,000 in now and you earn about $275 in the first six months. For comparison, the FDIC puts the national average savings rate at 0.38% and the average 12 month CD at 1.76%.
What are the catches?
- Your money is locked for a year. You cannot cash an I bond in its first 12 months.
- Leaving early costs a little. Cash out before five years and you give up the last three months of interest.
- There is a yearly cap. Each person can buy up to $10,000 in electronic I bonds per calendar year, only at TreasuryDirect.
- Taxes are lighter, not zero. Interest is subject to federal income tax but not state or local income tax, and you can wait to report it until you cash the bond.
Should you buy before Dec. 31?
The cap resets each calendar year. If you have not used your 2026 cap, buying now and again in January lets one person lock up to $20,000 at this fixed rate before the offer ends April 30. Bonds also earn interest from the first day of the month you buy, so buying late in a month still counts the whole month.
The quick take
The 5.51% headline will change in May. The 1.40% fixed rate will not. If you have cash you will not need for at least a year, this is the best I bond fixed rate since 2006.
Sources: TreasuryDirect, I bonds interest rates · TreasuryDirect, I bonds · TreasuryDirect, How much can I spend or own? · FDIC, National Rates and Rate Caps, October 2026. General information, not investment advice.


Leave a Reply